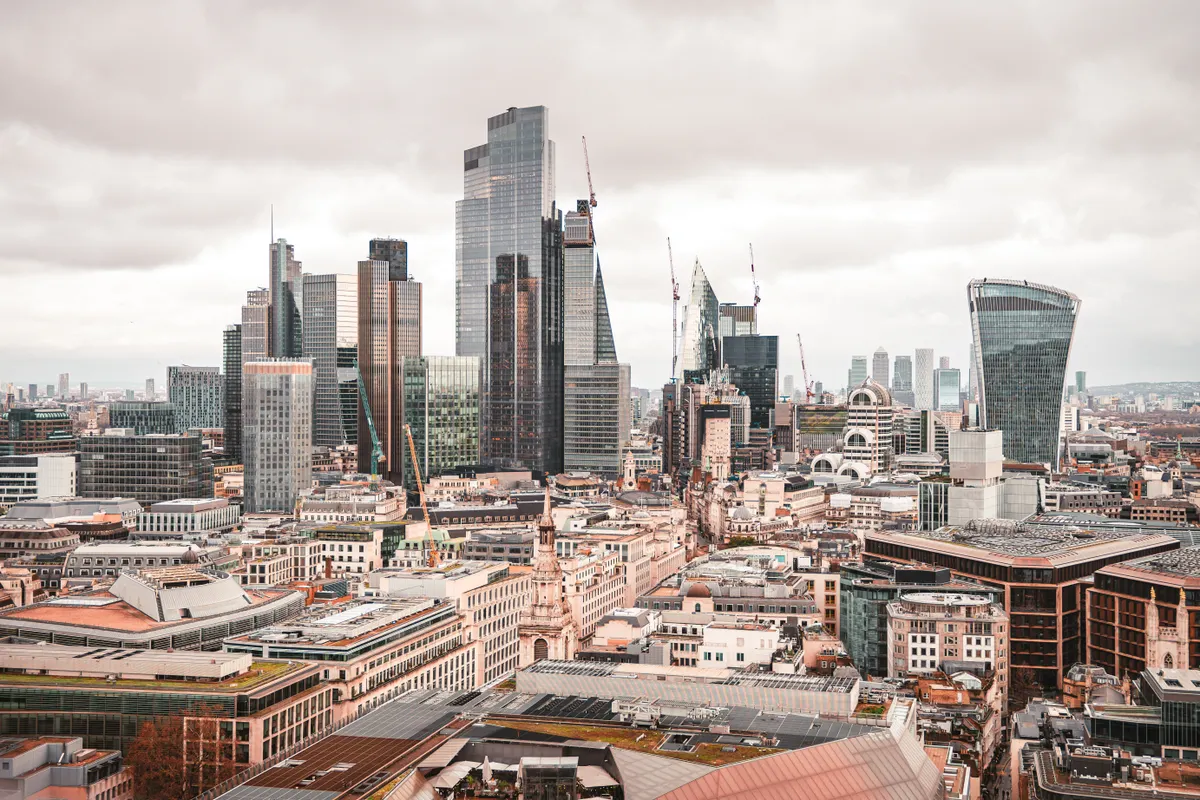

The Global Financial Centres Index confirms London’s position as the world’s second-ranked financial centre, but the rankings published by Z/Yen show a financial world shifting steadily eastward, leaving British policymakers with pointed questions about how long that position can be held.
New York remains at the top. London follows. But the six places immediately beneath it now belong to Hong Kong, Singapore, Shanghai, Tokyo, Seoul and Shenzhen. Zurich manages to squeeze into the top ten. Paris and Frankfurt, both once considered credible rivals to London’s dominance, have dropped out of the top 20 entirely.
What the Global Financial Centres Index reveals about London’s position
The thirty-sixth edition of the Global Financial Centres Index was published on 24 September 2024. It runs to considerable depth and is treated by market participants as a serious measure of competitive standing, not a promotional exercise. The broad picture it paints for London is one of resilience rather than advance: the city holds its ground while others close in.
Further down the rankings, the picture is more fluid still. San Francisco holds fifth place, with Chicago and Los Angeles now ranked sixth and seventh respectively, having overtaken Shanghai, which has slipped to eighth. That reshuffling among the American cities and Shanghai reflects a broader dynamism in the index that London, sitting comfortably in second, might be tempted to ignore. The case for complacency is weak.
The GFCI result arrived alongside Oxford Economics‘ latest Global Cities Index, which also places London second overall, again behind New York. The consultancy credits London’s economic strength, human capital and international connectivity for that ranking. There is one conspicuous drag on the figures: London’s housing costs pull its Quality of Life score down to 144th place, against Paris at seventh in the same category. Commercial muscle carries London up the overall table in spite of that.
Structural concerns behind the headline rankings
The rankings arrive at a moment of some unease among those who run the institutions that underpin London’s position. A recent private conversation among City chiefs touched on several overlapping problems: the size of the welfare bill, the cost of housing, the regulatory burden on parts of the economy, the relative unattractiveness of public markets, and broader hostility towards wealth creation. None of these is new. Few of them are being addressed with any urgency.
The political backdrop adds a further layer of uncertainty. A third Budget from the current Labour government is approaching, with the previous two having raised taxes by tens of billions of pounds. The possibility of a Reform government at some future point is being taken seriously in financial circles, whatever one’s view of the prospect. Taken together, these are not trivial concerns for institutions deciding where to invest, where to list and where to base their people.
The tightrope analogy is not an unfair one. London retains real advantages: depth of legal expertise, the English language, time-zone positioning between Asia and North America, a concentration of financial talent that has taken decades to accumulate. These are not easily replicated, and the GFCI and Global Cities Index both reflect them in their scores. But advantages are not guarantees. The eastern centres rising through the rankings are not doing so by accident, and Paris and Frankfurt’s fall from the top 20 is a reminder that established positions can erode.
The question of where Britain wants to be in these rankings in ten years’ time is one that the latest Global Financial Centres Index makes harder to defer. The index is published twice a year. The next edition will show whether London’s second place is a platform or a peak.
